
Audit firm SEO
Help buyers check your firm before they call
A finance director has your firm’s name but still needs to justify the choice. Can you do the work? Who would lead it? What supports your experience? Make those answers easy to find, check and share.
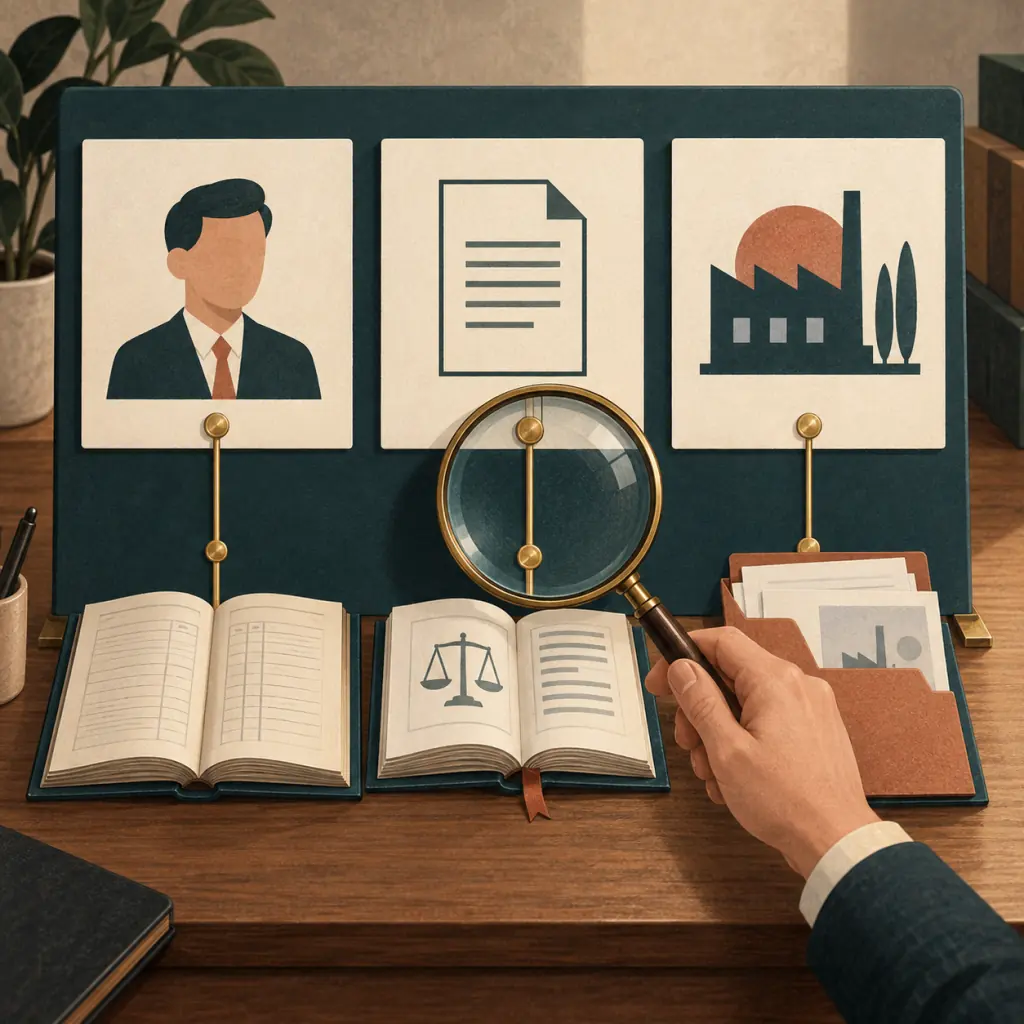
A claim is easier to assess when its supporting source is visible. The linked panels illustrate that relationship; they are not client evidence.
Turn a claim into something a buyer can check
A referral may bring someone to your website. A service or industry search may do the same. Both visitors need more than a claim that your firm is trustworthy.
Connect each important statement to evidence: a partner’s profile to the relevant professional register, a service to its scope and standards, sector experience to an approved account of actual work. Keep profiles, office details and contact routes consistent.
For a construction client, explain the reporting question your team has handled. For a nonprofit, explain the relevant engagement. Publish a case only after factual and confidentiality review; label invented examples as hypothetical.
This puts Google’s people-first content guidance to practical use: help the reader evaluate your firm, not just find its name.
Give buyers six answers before they enquire
Who can you serve?
Name the organisation types, industries and jurisdictions you cover. State important exclusions. A place-name page should reflect work you can actually undertake, not a location added to attract searches.
Which service is this?
Give financial-statement audits, internal audits, compliance engagements and other services their own clear descriptions. If you offer SOC 2 examinations or US retirement-plan audits, explain those specific services rather than hiding them under a general audit label.
Which requirements apply?
Identify the relevant framework, jurisdiction and reporting period. Have the responsible professional check the applicable edition. Explain what a standard means for this buyer instead of listing unexplained acronyms.
Who would lead the work?
Name the relevant partner and document the team’s qualifications and experience. Link appropriate registration or licence records. Explain how a buyer can ask about the proposed team; do not imply that a named person is already assigned.
What goes in, and what comes out?
Describe likely preparation, client inputs and the type of report or deliverable. Separate an illustrative outline from the scope to be agreed. Never promise a favourable opinion or finding.
What happens after contact?
Explain the first discussion of scope and timing, followed by the firm’s acceptance and applicable independence checks. Keep tax and bookkeeping enquiries distinct where you offer those services. An enquiry is not an agreed engagement.
The first message opens a discussion. Confidential records need a separate, agreed sharing process. The desk and cabinet are a visual metaphor.
Ask for a useful brief, not the financial records
Imagine a nonprofit finance lead who needs to discuss a reporting requirement. This is a hypothetical example, not a client case or a conclusion that an audit is required.
A first enquiry could identify:
- Organisation: its type and jurisdiction.
- Requirement: the requested report and who requires it.
- Period: the financial or reporting period.
- Timing: the requested completion date.
- Contact: the person coordinating the discussion.
Ask people not to send confidential financial records through a general contact form. After clarifying the request, the firm can explain what further information is needed and how to share it appropriately.
Do not use “audit” for two different promises
Financial-statement audit
Under ISA 200, the auditor seeks reasonable assurance that the financial statements as a whole are free of material misstatement, whether from fraud or error. The auditor expresses an opinion under the applicable reporting framework.
Reasonable assurance is high, not absolute. Do not describe an audit as a guarantee of perfect accounts or detection of every error and fraud.
Agreed-upon procedures
Under ISRS 4400 (Revised), the practitioner performs agreed procedures and reports the findings. The intended users draw their own conclusions.
This is not an audit opinion or an assurance conclusion. Explain the actual service and deliverable instead of suggesting that the two engagements are interchangeable.
Use the standards that apply to your work. The IESBA Code is an international professional reference for truthful marketing and independence, not a replacement for local rules. Your qualified reviewer must check service claims and acceptance requirements.
An old search term still needs a current answer
US example: a firm serving organisations that spend federal awards may receive enquiries using the old term “A-133 audit”. Explain the current service with links to Uniform Guidance: 2 CFR Part 200, Subpart F and the Federal Audit Clearinghouse. Do not present the historical label as the current rule.
For work under Government Auditing Standards, link to GAO’s Yellow Book guidance. The applicable edition depends on the work and its effective dates, not simply the year printed on your webpage. Have the responsible professional check it.
State the jurisdiction, identify the author or technical reviewer and show when the guidance was checked. Link to current eligibility requirements rather than leaving an undated threshold on a general marketing page.
Test the page with a buyer’s task
Give someone outside the website project a fictional organisation and ask them to use a phone:
- Find the relevant service and jurisdiction.
- Identify the responsible partner and supporting credentials.
- Find the requirements, preparation and scope limits.
- Prepare the questions still needed before an engagement can be discussed.
Then coordinate a test enquiry with your team. Check that it arrives and that the reply route is clear. Repair the missing answer before adding another page.
Count progress towards a suitable engagement
Review search queries and landing pages against the services, industries and jurisdictions you actually cover. Record broad enquiry fit without putting sensitive prospect details into marketing reports.
Keep evidence-link clicks, received enquiries, accepted opportunities and agreed engagements separate. Rankings and time on the page do not establish that a client is suitable. Google warns against guaranteed first-place rankings.
Start with one question your team repeatedly answers by email. Put the verified answer on the service page and repeat the buyer test.
Make your audit service easier to evaluate
Bring one service page and the question prospective clients keep asking. We can help make the scope, evidence and next step clearer, with professional claims checked by your firm’s reviewer.